Ctrl+K
financialkit logo financialkit logo
  • Subpackages
  • History
  • Examples
  • API
  • GitHub
  • PyPI
  • Subpackages
  • History
  • Examples
  • API
  • GitHub
  • PyPI

Section Navigation

  • O’Kane and Turnbull: the CDS par spread
  • The ISDA standard model: bootstrapping hazard rates
  • Credit default swaps

Credit default swaps#

Pricing protection, and reading default probabilities off quotes.
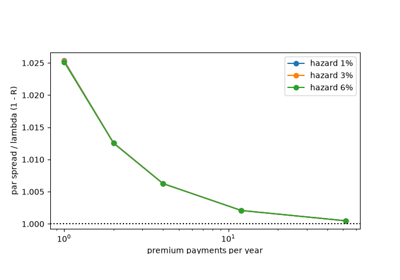
O’Kane and Turnbull: the CDS par spread

O'Kane and Turnbull: the CDS par spread

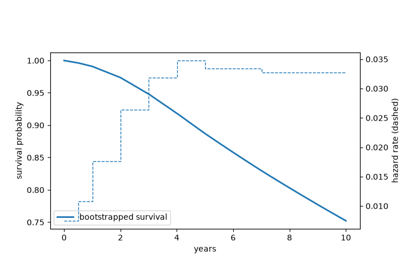
The ISDA standard model: bootstrapping hazard rates

The ISDA standard model: bootstrapping hazard rates

Show Source

© Copyright 2026, financialkit contributors.

Created using Sphinx 9.1.0.

Built with the PyData Sphinx Theme 0.23.0.