Ctrl+K
financialkit logo financialkit logo
  • Subpackages
  • History
  • Examples
  • API
  • GitHub
  • PyPI
  • Subpackages
  • History
  • Examples
  • API
  • GitHub
  • PyPI

Section Navigation

  • Sklar’s theorem and the Gaussian copula
  • Demarta-McNeil: the t copula and tail dependence
  • Copulas

Copulas#

Dependence separated from the marginals, and the joint extremes that the Gaussian copula misses.

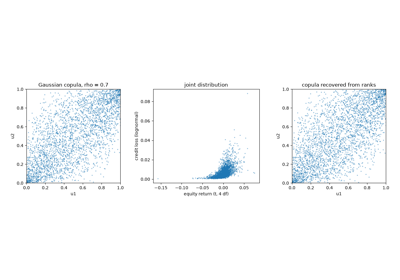
Sklar’s theorem and the Gaussian copula

Sklar's theorem and the Gaussian copula

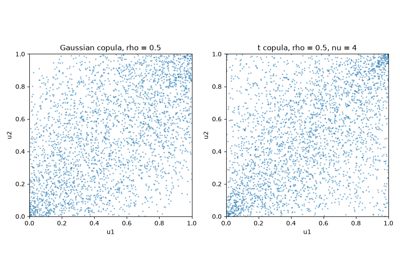
Demarta-McNeil: the t copula and tail dependence

Demarta-McNeil: the t copula and tail dependence

Show Source

© Copyright 2026, financialkit contributors.

Created using Sphinx 9.1.0.

Built with the PyData Sphinx Theme 0.23.0.