Ctrl+K
financialkit logo financialkit logo
  • Subpackages
  • History
  • Examples
  • API
  • GitHub
  • PyPI
  • Subpackages
  • History
  • Examples
  • API
  • GitHub
  • PyPI

Section Navigation

  • Hull and White’s stochastic volatility
  • The Heston model
  • Stochastic volatility

Stochastic volatility#

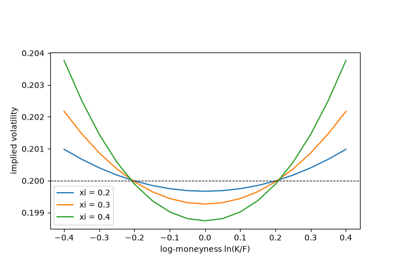
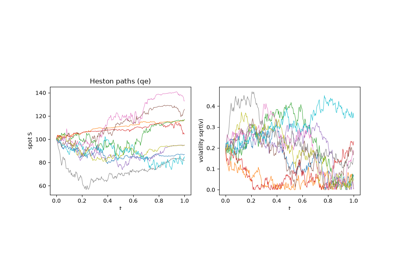
Volatility with its own randomness: Hull and White’s mixing formula for uncorrelated variance, and Heston’s correlated square-root model.

Hull and White’s stochastic volatility

Hull and White's stochastic volatility

The Heston model

The Heston model
Show Source

© Copyright 2026, financialkit contributors.

Created using Sphinx 9.1.0.

Built with the PyData Sphinx Theme 0.23.0.