Ctrl+K
financialkit logo financialkit logo
  • Subpackages
  • History
  • Examples
  • API
  • GitHub
  • PyPI
  • Subpackages
  • History
  • Examples
  • API
  • GitHub
  • PyPI

Section Navigation

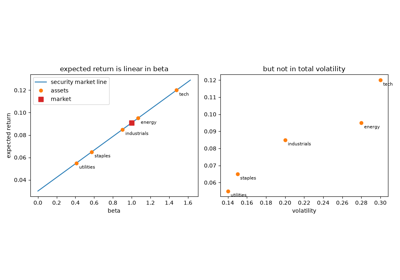
  • Sharpe’s CAPM and the security market line
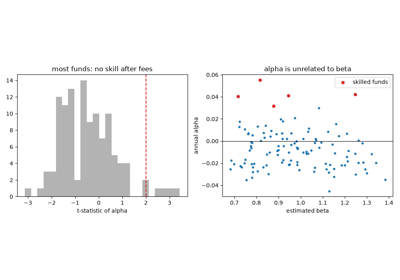
  • Jensen’s alpha
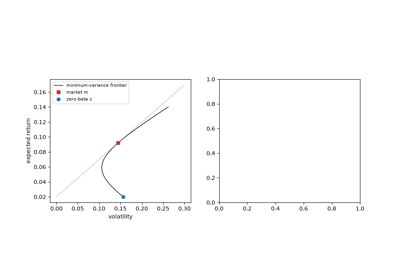
  • Black’s zero-beta CAPM
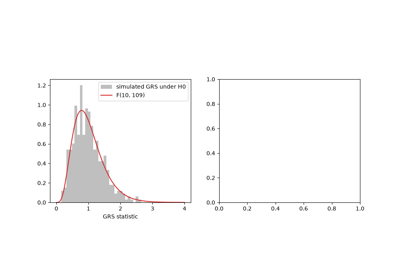
  • The Gibbons-Ross-Shanken test
  • The CAPM

The CAPM#

The security market line, performance measurement with Jensen’s alpha, the zero-beta CAPM without a riskless asset, and the exact test of whether a portfolio is mean-variance efficient.

Sharpe’s CAPM and the security market line

Sharpe's CAPM and the security market line

Jensen’s alpha

Jensen's alpha

Black’s zero-beta CAPM

Black's zero-beta CAPM

The Gibbons-Ross-Shanken test

The Gibbons-Ross-Shanken test
Show Source

© Copyright 2026, financialkit contributors.

Created using Sphinx 9.1.0.

Built with the PyData Sphinx Theme 0.23.0.