
Note
Go to the end to download the full example code or to run this example in your browser via JupyterLite.
Ross’s arbitrage pricing theory#
Stephen Ross (1976) derived linear pricing without an equilibrium model. If returns follow a factor model \(r_i = E[r_i] + \beta_i' f + \varepsilon_i\) with diversifiable \(\varepsilon_i\), then any asset off the plane \(E[r_i] = r_f + \beta_i'\lambda\) can be combined with others into a portfolio with no cost and no factor risk that still earns a positive expected return. In a large market its idiosyncratic risk diversifies away, and the portfolio becomes an arbitrage. The pricing errors therefore have to be small for all but finitely many assets.
import matplotlib.pyplot as plt
import numpy as np

from financialkit.asset_pricing import apt_arbitrage_portfolio, apt_expected_returns

rng = np.random.default_rng(1976)
lam = np.array([0.05, 0.02])
idio = 0.25

sizes = np.array([10, 30, 100, 300, 1000, 3000])
sharpe = []
for n in sizes:
    B = np.column_stack([rng.uniform(0.5, 1.5, n), rng.normal(0, 1, n)])
    mu = apt_expected_returns(B, lam, 0.03) + rng.normal(0, 0.01, n)  # 1% pricing errors
    w = apt_arbitrage_portfolio(mu, B)
    sharpe.append((w @ mu) / (idio * np.linalg.norm(w)))
    if n == 100:
        print(f"n = 100: cost {w.sum():.1e}, factor exposure {np.abs(w @ B).max():.1e}, expected return {w @ mu:.4f}")

fig, ax = plt.subplots(figsize=(7, 4))
ax.loglog(sizes, sharpe, "o-", label="arbitrage portfolio")
ax.loglog(sizes, sharpe[0] * np.sqrt(sizes / sizes[0]), "k:", label="~ sqrt(n)")
ax.set_xlabel("number of assets")
ax.set_ylabel("Sharpe ratio of the zero-cost, zero-beta portfolio")
ax.set_title("constant pricing errors allow unbounded Sharpe ratios")
ax.legend()
fig.tight_layout()
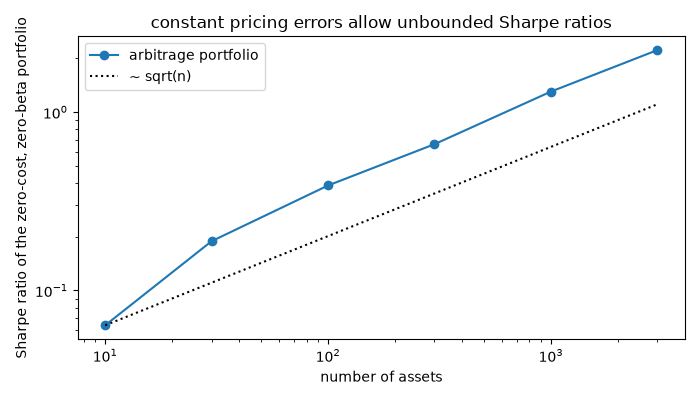
n = 100: cost 1.9e-15, factor exposure 2.1e-15, expected return 0.0094
When pricing errors die out#
If only a handful of assets are mispriced, the Sharpe ratio stays bounded.
sharpe_sparse = []
for n in sizes:
    B = np.column_stack([rng.uniform(0.5, 1.5, n), rng.normal(0, 1, n)])
    err = np.zeros(n)
    err[:5] = 0.01
    mu = apt_expected_returns(B, lam, 0.03) + err
    w = apt_arbitrage_portfolio(mu, B)
    sharpe_sparse.append((w @ mu) / (idio * np.linalg.norm(w)))
ax.loglog(sizes, sharpe_sparse, "s-", label="five mispriced assets")
ax.legend()

plt.show()
Total running time of the script: (0 minutes 0.059 seconds)
