Ctrl+K
financialkit logo financialkit logo
  • Subpackages
  • History
  • Examples
  • API
  • GitHub
  • PyPI
  • Subpackages
  • History
  • Examples
  • API
  • GitHub
  • PyPI

Section Navigation

  • Merton’s structural model
  • Black and Cox: default at the first passage
  • Leland’s endogenous default and optimal leverage
  • Crosbie and Bohn: the distance to default
  • Structural models

Structural models#

Default as an option on the firm’s assets: at maturity, at a barrier, or when shareholders choose.

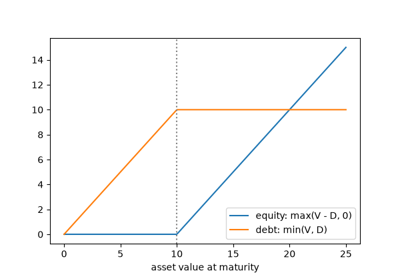
Merton’s structural model

Merton's structural model

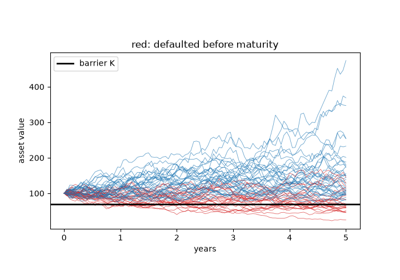
Black and Cox: default at the first passage

Black and Cox: default at the first passage

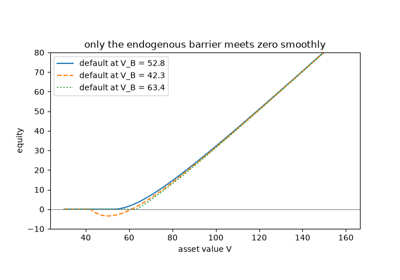
Leland’s endogenous default and optimal leverage

Leland's endogenous default and optimal leverage

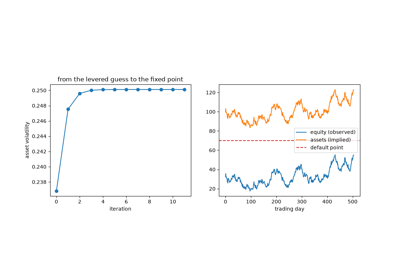
Crosbie and Bohn: the distance to default

Crosbie and Bohn: the distance to default

Show Source

© Copyright 2026, financialkit contributors.

Created using Sphinx 9.1.0.

Built with the PyData Sphinx Theme 0.23.0.