Backtesting#
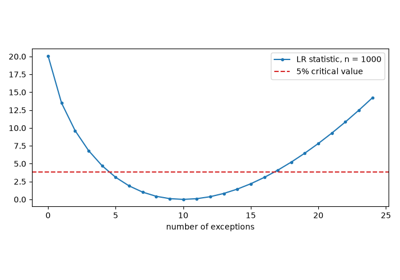
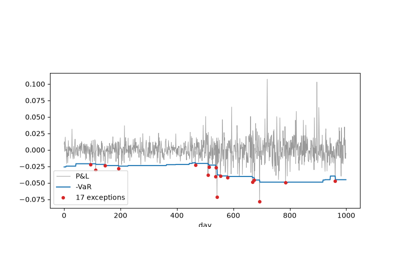
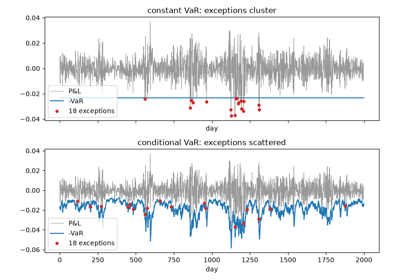
Checking a VaR model against realised losses: the number of exceptions, the regulator’s zones and whether exceptions cluster.

Checking a VaR model against realised losses: the number of exceptions, the regulator’s zones and whether exceptions cluster.