Factor models#
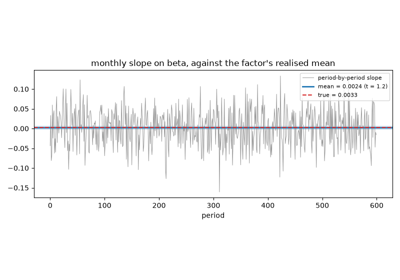
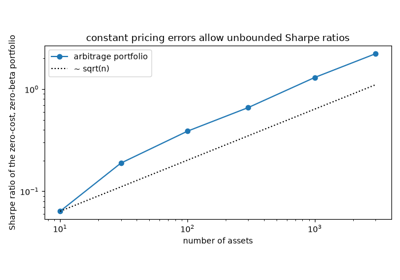
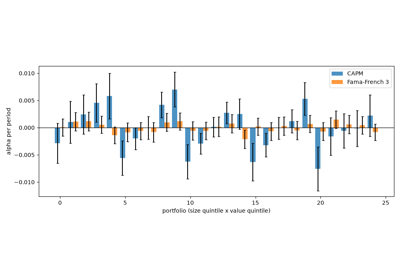
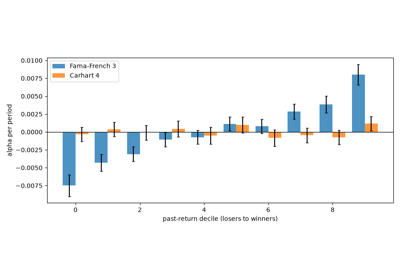
Estimating risk premia from the cross-section, the arbitrage argument for linear pricing, and factors built by sorting stocks on size, value and momentum.

Estimating risk premia from the cross-section, the arbitrage argument for linear pricing, and factors built by sorting stocks on size, value and momentum.