Ctrl+K
financialkit logo financialkit logo
  • Subpackages
  • History
  • Examples
  • API
  • GitHub
  • PyPI
  • Subpackages
  • History
  • Examples
  • API
  • GitHub
  • PyPI

Section Navigation

  • Vasicek’s large homogeneous portfolio
  • CreditRisk+ and Panjer’s recursion
  • Li’s Gaussian copula for default times
  • The Basel II IRB formula
  • Hull and White: pricing CDO tranches without Monte Carlo
  • Portfolio losses

Portfolio losses#

Correlated defaults, loss distributions, regulatory capital and tranches.
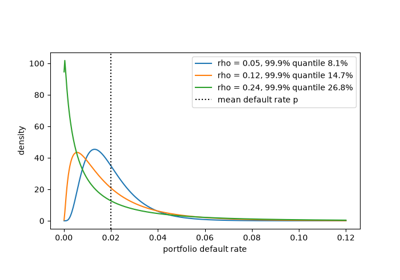
Vasicek’s large homogeneous portfolio

Vasicek's large homogeneous portfolio

CreditRisk+ and Panjer’s recursion

CreditRisk+ and Panjer's recursion

Li’s Gaussian copula for default times

Li's Gaussian copula for default times

The Basel II IRB formula

The Basel II IRB formula

Hull and White: pricing CDO tranches without Monte Carlo

Hull and White: pricing CDO tranches without Monte Carlo

Show Source

© Copyright 2026, financialkit contributors.

Created using Sphinx 9.1.0.

Built with the PyData Sphinx Theme 0.23.0.