Ctrl+K
financialkit logo financialkit logo
  • Subpackages
  • History
  • Examples
  • API
  • GitHub
  • PyPI
  • Subpackages
  • History
  • Examples
  • API
  • GitHub
  • PyPI

Section Navigation

  • Markowitz’s mean-variance frontier
  • Tobin separation and the tangency portfolio
  • Merton’s analytic frontier
  • DeMiguel-Garlappi-Uppal: optimal versus 1/N
  • Mean-variance

Mean-variance#

Portfolios with the least variance for their mean, with and without short sales and a riskless asset, and the naive benchmark they struggle to beat out of sample.

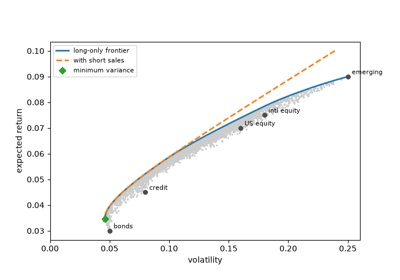
Markowitz’s mean-variance frontier

Markowitz's mean-variance frontier

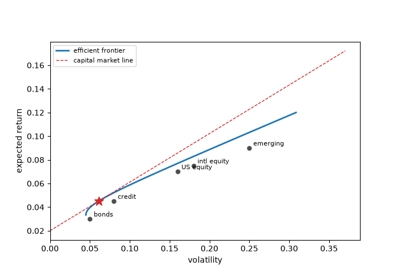
Tobin separation and the tangency portfolio

Tobin separation and the tangency portfolio

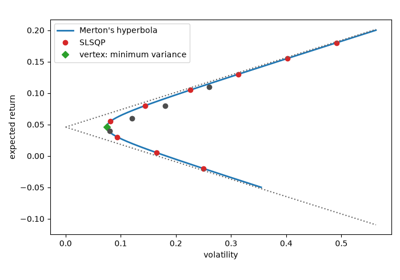
Merton’s analytic frontier

Merton's analytic frontier

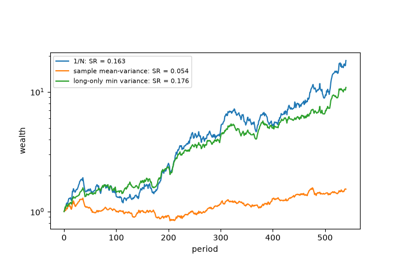
DeMiguel-Garlappi-Uppal: optimal versus 1/N

DeMiguel-Garlappi-Uppal: optimal versus 1/N
Show Source

© Copyright 2026, financialkit contributors.

Created using Sphinx 9.1.0.

Built with the PyData Sphinx Theme 0.23.0.