Value at risk#

The loss that is exceeded with a given small probability, estimated in closed form, by expansion, by simulation and from weighted or filtered history.

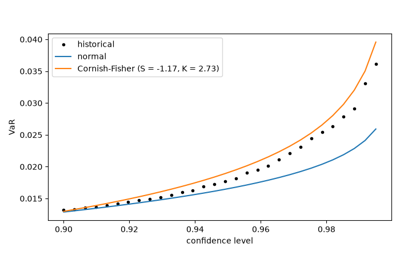
Cornish-Fisher: VaR beyond the normal

Cornish-Fisher: VaR beyond the normal

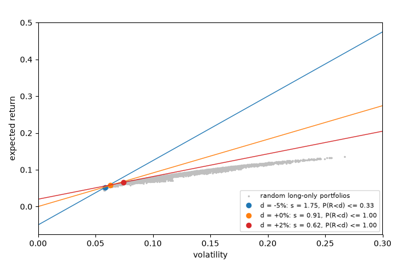
Roy’s safety-first criterion

Roy's safety-first criterion

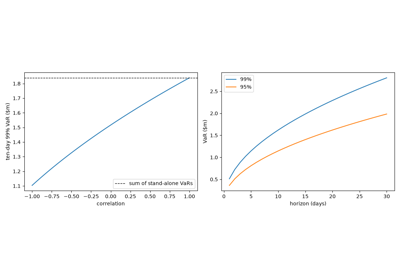
RiskMetrics: parametric (delta-normal) VaR

RiskMetrics: parametric (delta-normal) VaR

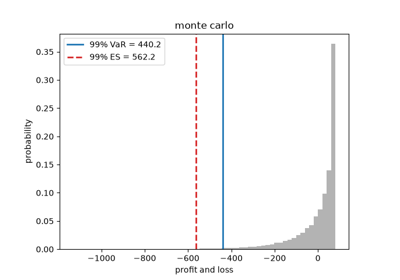
Pritsker: Monte Carlo VaR for option books

Pritsker: Monte Carlo VaR for option books

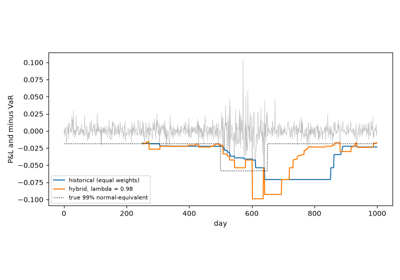
Boudoukh-Richardson-Whitelaw hybrid VaR

Boudoukh-Richardson-Whitelaw hybrid VaR

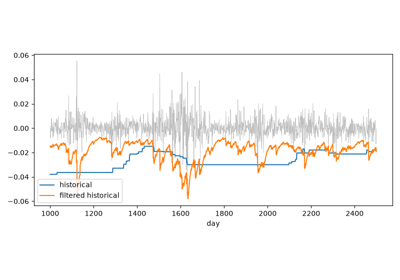
Barone-Adesi: filtered historical simulation

Barone-Adesi: filtered historical simulation