
Note
Go to the end to download the full example code or to run this example in your browser via JupyterLite.
SIA 30/360 and accrued interest#
A bond buyer pays the seller the coupon interest earned since the last coupon date. The Securities Industry Association’s Standard Securities Calculation Methods (1993) codified how U.S. corporate and agency bonds count those days: every month has 30 days and the year 360, with rules for the 31st and for the end of February. The example is Hull’s: a 10% bond with coupons on March 1 and September 1, bought for settlement on July 3, 2018.
import matplotlib.pyplot as plt
import numpy as np

from financialkit.time_value import accrued_interest, day_count
Hull’s example#
last, settle, nxt = "2018-03-01", "2018-07-03", "2018-09-01"
print(f"30/360 days: {day_count(last, settle, '30/360 US')} of {day_count(last, nxt, '30/360 US')}")
print(f"actual days: {day_count(last, settle, 'ACT/360')} of {day_count(last, nxt, 'ACT/360')}")
print(f"accrued interest per 100: {accrued_interest(100.0, 0.10, last, settle, '30/360 US'):.4f}")
30/360 days: 122 of 180
actual days: 124 of 184
accrued interest per 100: 3.3889
The end-of-month rules#
2023-01-31 -> 2023-03-31: 30/360 US 60, 30E/360 60
2023-01-15 -> 2023-03-31: 30/360 US 76, 30E/360 75
2023-02-28 -> 2023-08-31: 30/360 US 180, 30E/360 182
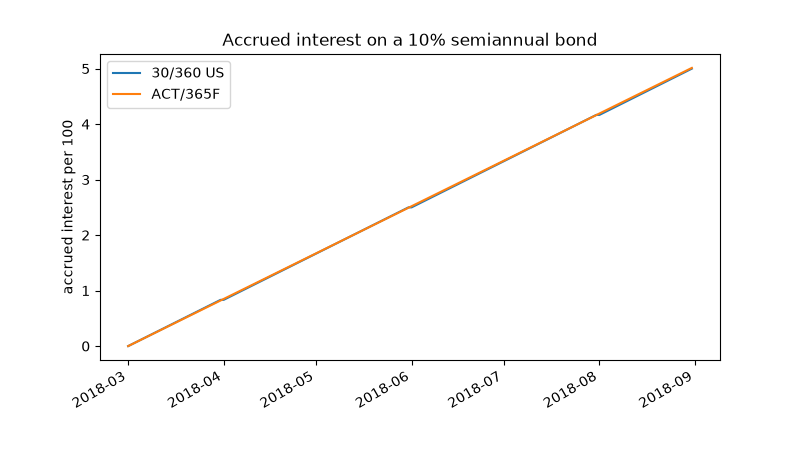
Accrued interest through a coupon period#
30/360 accrues the same amount every month; actual days do not.
settles = np.arange(np.datetime64("2018-03-01"), np.datetime64("2018-09-01"))
fig, ax = plt.subplots(figsize=(8, 4.5))
ax.plot(settles, accrued_interest(100.0, 0.10, last, settles, "30/360 US"), label="30/360 US")
ax.plot(settles, accrued_interest(100.0, 0.10, last, settles, "ACT/365F"), label="ACT/365F")
ax.set_ylabel("accrued interest per 100")
ax.set_title("Accrued interest on a 10% semiannual bond")
ax.legend()
fig.autofmt_xdate()

plt.show()
Total running time of the script: (0 minutes 0.030 seconds)
