Variance reduction#
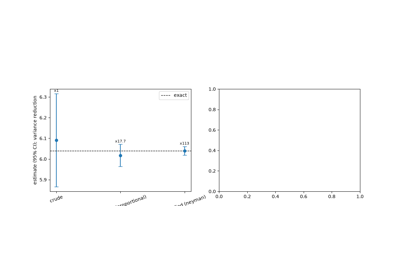
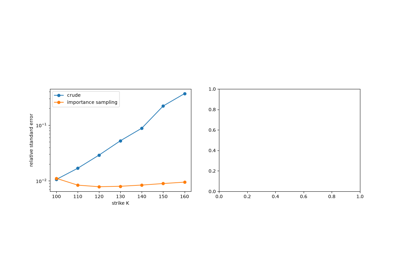
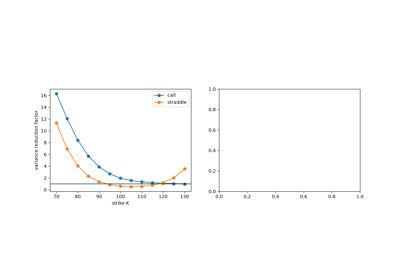
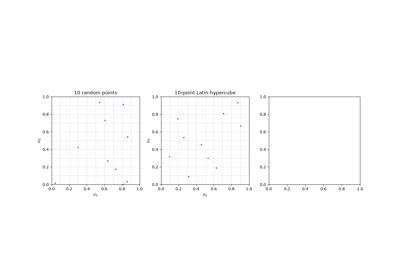
The same expectation from fewer samples: stratification, importance sampling, antithetic variates, Latin hypercubes, control variates and moment matching, each compared with crude Monte Carlo.

The same expectation from fewer samples: stratification, importance sampling, antithetic variates, Latin hypercubes, control variates and moment matching, each compared with crude Monte Carlo.