Short-rate models#
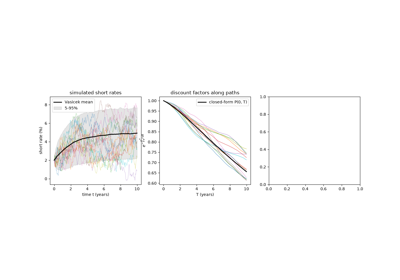
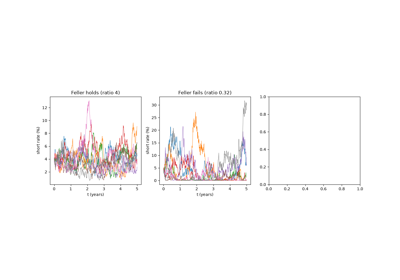
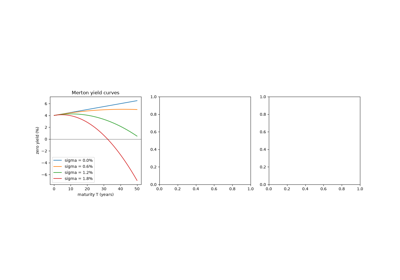
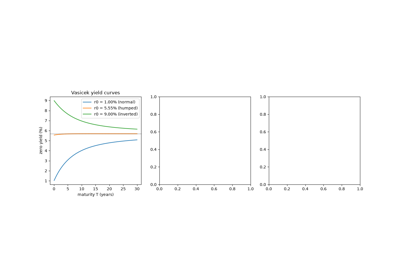
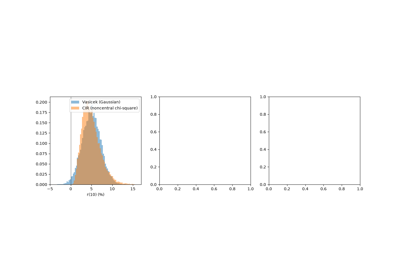
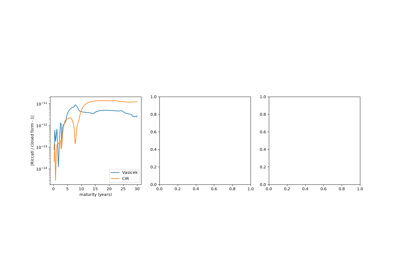
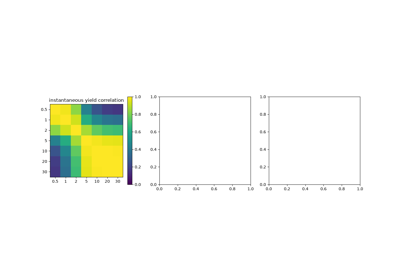
Models of the instantaneous short rate that produce their own yield curve: Merton, Vasicek and Cox-Ingersoll-Ross, the affine family that contains them, and the two-factor G2++, all checked against Feynman-Kac Monte Carlo.

Models of the instantaneous short rate that produce their own yield curve: Merton, Vasicek and Cox-Ingersoll-Ross, the affine family that contains them, and the two-factor G2++, all checked against Feynman-Kac Monte Carlo.