
Note
Go to the end to download the full example code or to run this example in your browser via JupyterLite.
Jamshidian’s swap market model: Black swaptions#
Jamshidian (1997) showed that the market’s way of quoting swaptions is also exact in a model of its own. Under the measure that uses the swap’s fixed-leg annuity \(A = \sum_i \tau_i P(0, t_i)\) as numeraire, the forward swap rate \(S = [P(0, T_0) - P(0, T_n)]/A\) is a martingale, and if it is lognormal a payer swaption is
Black’s formula on the swap rate, times the annuity. The swap market model and the LIBOR market model cannot both be lognormal, but each prices its own instruments exactly.
import matplotlib.pyplot as plt
import numpy as np

from financialkit.fixed_income import NelsonSiegelCurve
from financialkit.interest_rate_models import HullWhiteModel, black_swaption_price, forward_swap_annuity, forward_swap_rate, jamshidian_swaption
from financialkit.options import implied_volatility
Hull’s example#
Hull (Example 29.5): a 5-year option to pay 6.2% on a 3-year semiannual swap, curve flat at 6% continuously compounded, 20% volatility, principal 100.
print(f"payer swaption: {black_swaption_price(0.06, 5.0, 3.0, 0.062, 0.2, 2, notional=100.0):.2f} (Hull: 2.07)")
payer swaption: 2.07 (Hull: 2.07)
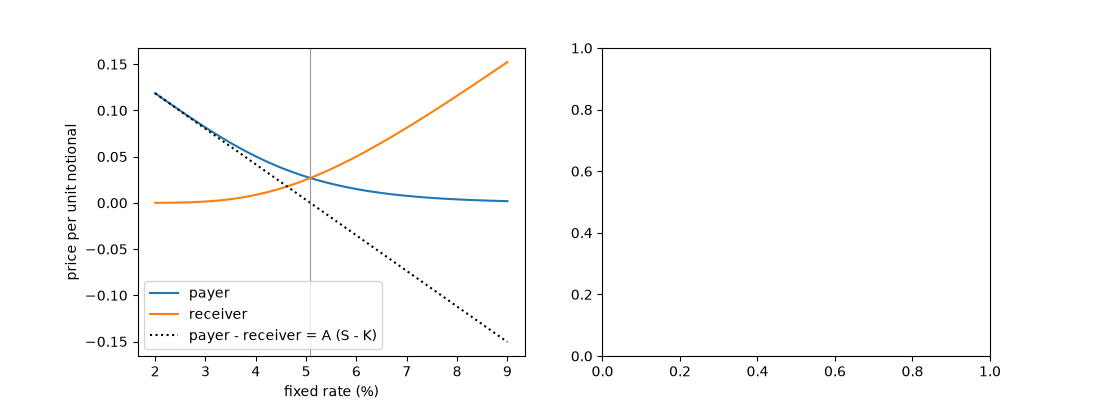
Payer, receiver and parity#
curve = NelsonSiegelCurve(0.05, -0.02, 0.01, 2.0)
expiry, tenor = 3.0, 5.0
S, A = forward_swap_rate(curve, expiry, tenor), forward_swap_annuity(curve, expiry, tenor)
K = np.linspace(0.02, 0.09, 50)
payer = black_swaption_price(curve, expiry, tenor, K, 0.2)
receiver = black_swaption_price(curve, expiry, tenor, K, 0.2, payer=False)
fig, axes = plt.subplots(1, 2, figsize=(11, 4))
axes[0].plot(100 * K, payer, label="payer")
axes[0].plot(100 * K, receiver, label="receiver")
axes[0].plot(100 * K, payer - receiver, "k:", label="payer - receiver = A (S - K)")
axes[0].axvline(100 * S, color="0.6", lw=0.8)
axes[0].set_xlabel("fixed rate (%)")
axes[0].set_ylabel("price per unit notional")
axes[0].legend()
print(f"max parity error: {np.max(np.abs(payer - receiver - A * (S - K))):.1e}")
max parity error: 4.2e-17
The Black volatilities a Hull-White model quotes#
Price swaptions exactly in Hull-White by Jamshidian’s decomposition, then invert Black’s formula: the model’s volatility smile in swap-rate terms is downward sloping, the signature of a normal (Gaussian) model.
hw = HullWhiteModel(curve, 0.1, 0.01)
for tenor_ in (2.0, 5.0, 10.0):
    S_, A_ = forward_swap_rate(curve, expiry, tenor_), forward_swap_annuity(curve, expiry, tenor_)
    Ks = S_ + np.linspace(-0.02, 0.02, 9)
    prices = np.array([jamshidian_swaption(hw, expiry, tenor_, k).price for k in Ks])
    vols = implied_volatility(prices / A_, S_, Ks, expiry, 0.0, 0.0)
    axes[1].plot(100 * (Ks - S_), 100 * vols, "o-", ms=3, label=f"3y x {tenor_:g}y")
axes[1].set_xlabel("strike - forward swap rate (%)")
axes[1].set_ylabel("Black swaption volatility (%)")
axes[1].legend(title="Hull-White a = 0.1, sigma = 1%")
fig.tight_layout()

plt.show()
Total running time of the script: (0 minutes 0.075 seconds)
