Curve-fitted models#
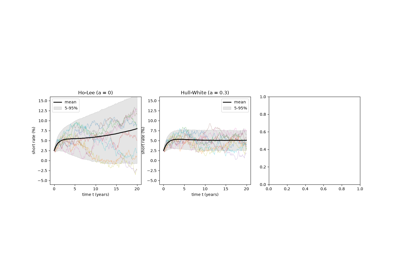
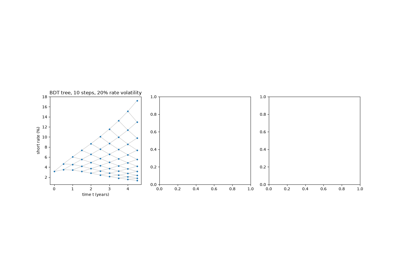
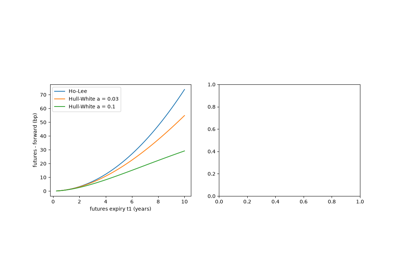
Arbitrage-free models that take today’s yield curve as an input: Ho-Lee, Hull-White and the Black-Derman-Toy tree, and the convexity gap between futures and forward rates that they predict.
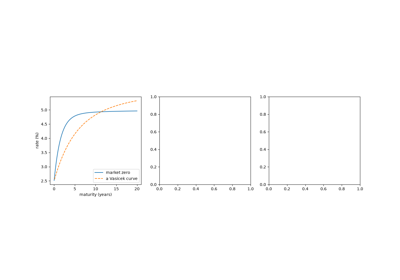
Ho-Lee: the first arbitrage-free term-structure model
Ho-Lee: the first arbitrage-free term-structure model