
Note
Go to the end to download the full example code.
Chebyshev’s inequality: one bound for every distribution#
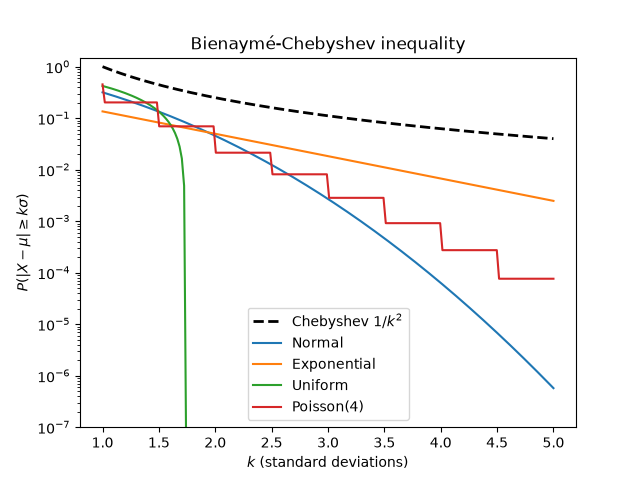
\(P(|X-\mu| \geq k\sigma) \leq 1/k^2\) holds for any distribution with finite variance. Comparing it with exact tails shows how conservative a universal bound has to be.
import matplotlib.pyplot as plt
import numpy as np

from mathematicskit.probability import Exponential, Normal, Poisson, Uniform, chebyshev_tail
Exact tails against the bound#
k = np.linspace(1.0, 5.0, 200)
fig, ax = plt.subplots()
ax.semilogy(k, 1.0 / k**2, "k--", lw=2, label=r"Chebyshev $1/k^2$")
for name, dist in [("Normal", Normal(0.0, 1.0)), ("Exponential", Exponential(rate=1.0)), ("Uniform", Uniform(0.0, 1.0)), ("Poisson(4)", Poisson(mu=4.0))]:
    result = chebyshev_tail(dist, k)
    ax.semilogy(k, np.maximum(result.exact, 1e-8), label=name)
ax.set_ylim(1e-7, 1.5)
ax.set_xlabel(r"$k$ (standard deviations)")
ax.set_ylabel(r"$P(|X-\mu| \geq k\sigma)$")
ax.legend()
ax.set_title("Bienaymé-Chebyshev inequality")

print(chebyshev_tail(Normal(0.0, 1.0), [2.0, 3.0]))
TailBoundResult(k=array([2., 3.]), bound=array([0.25 , 0.11111111]), exact=array([0.04550026, 0.0026998 ]))
Total running time of the script: (0 minutes 0.068 seconds)