Examples#
This gallery walks through every public feature of financialkit.time_series:
the stylized facts of returns, tests of the random walk, ARMA models and
order selection, unit roots and cointegration, long memory, and
conditional-volatility models. Each script illustrates one dated
breakthrough from the history page.
All data are synthetic and seeded; no market data is downloaded.
See also the narrative tutorial:
Each script in this gallery is self-contained and can be run directly with
python examples/time_series/<section>/<script>.py.
Sections#
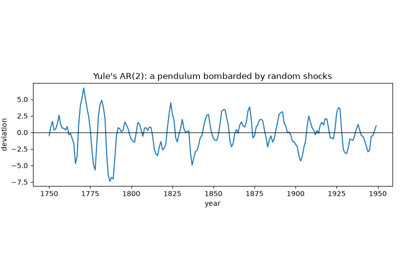
linear_models – Yule’s autoregression, Box-Jenkins ARMA and Akaike’s information criterion.
long_memory – Hurst’s rescaled range.
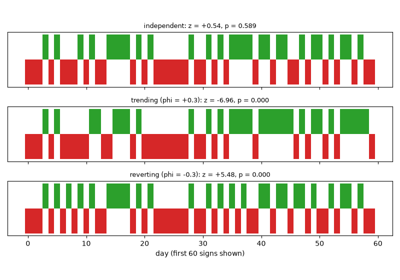
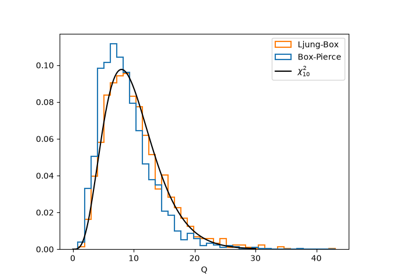
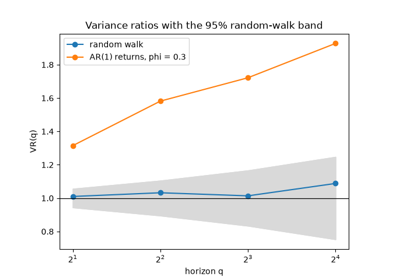
efficiency – Kendall’s serial correlations, Fama’s runs test, the Ljung-Box portmanteau test and Lo-MacKinlay variance ratios.
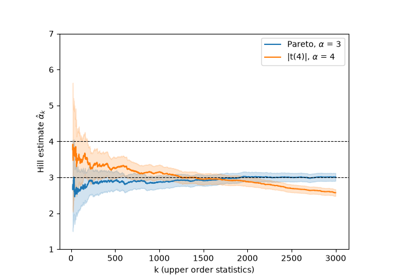
stylized_facts – Mandelbrot’s fat tails and the Hill tail index.
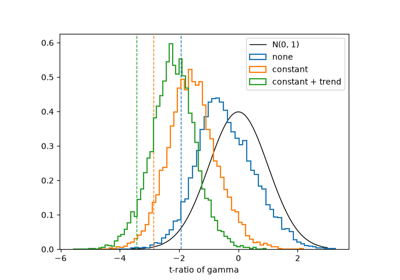
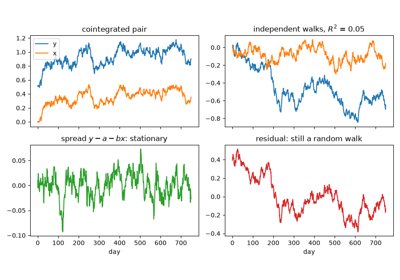
unit_roots – the Dickey-Fuller test and Engle-Granger cointegration.
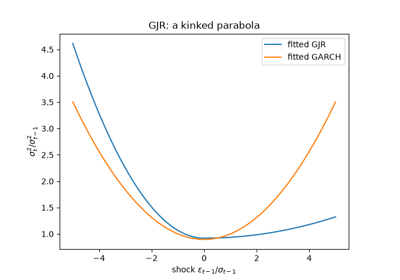
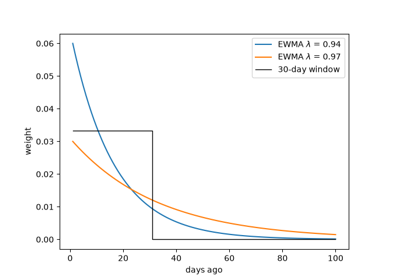
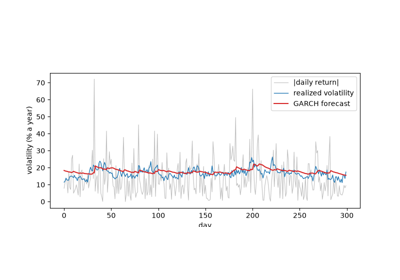
volatility – Parkinson’s range, ARCH, GARCH, EGARCH, GJR-GARCH, RiskMetrics EWMA and realized volatility.
Market efficiency#
Testing the random walk: serial correlation, runs, portmanteau statistics and variance ratios.
Linear models#
From Yule’s disturbed pendulum to Box-Jenkins ARMA and Akaike’s criterion.
Long memory#
Hurst’s rescaled range and fractional Gaussian noise.
Stylized facts#
Fat tails and the tail index.
Unit roots and cointegration#
The Dickey-Fuller distribution and the Engle-Granger two-step test.
Volatility#
Range-based and realized volatility, and the ARCH family of conditional-variance models.