Stochastic processes#
Brownian motion and the Einstein relation, Langevin dynamics and the fluctuation-dissipation balance, the Fokker-Planck equation for the probability density, the Ornstein-Uhlenbeck process, and the Euler-Maruyama and Milstein schemes that integrate Itô stochastic differential equations.
Einstein’s Brownian motion: diffusion equals mobility times temperature
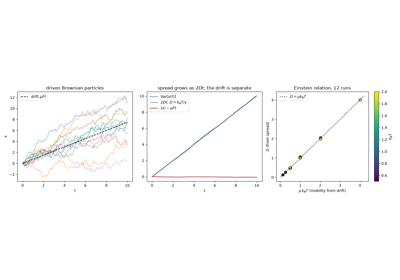
Einstein's Brownian motion: diffusion equals mobility times temperature
The Fokker-Planck equation: from noisy trajectories to a deterministic density
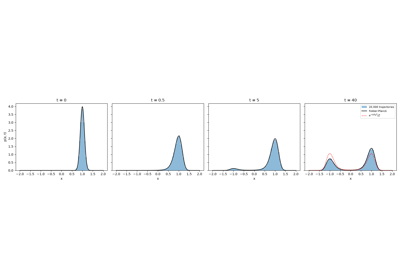
The Fokker-Planck equation: from noisy trajectories to a deterministic density
Itô’s stochastic calculus: the Euler-Maruyama and Milstein schemes
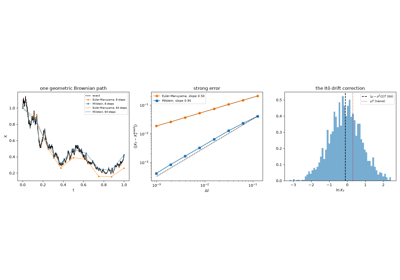
Itô's stochastic calculus: the Euler-Maruyama and Milstein schemes
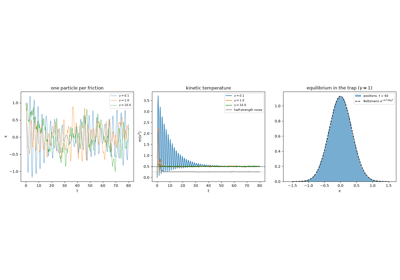
The Langevin equation: friction and noise must balance
The Langevin equation: friction and noise must balance
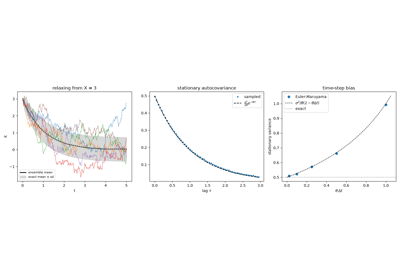
The Ornstein-Uhlenbeck process: Gaussian noise with a memory
The Ornstein-Uhlenbeck process: Gaussian noise with a memory