
Examples#
This gallery walks through every public feature of mathematicskit.optimization:
gradient descent, nonlinear conjugate gradient, Newton’s method and BFGS,
momentum methods (Nesterov, Adam), Nelder-Mead, golden-section search,
stochastic approximation, nonlinear least squares, constrained
optimization (Lagrange/KKT, the penalty method, Frank-Wolfe), linear and
integer programming, zero-sum games, and dynamic programming.
See also the narrative tutorial:
Each script in this gallery is self-contained and can be run directly with
python examples/optimization/<section>/<script>.py.
Sections#
gradient_descent – fixed-step and backtracking-line-search gradient descent.
conjugate_gradient – nonlinear conjugate gradient (Fletcher-Reeves, Polak-Ribiere).
newton_quasi_newton – Newton’s method and BFGS on the Rosenbrock function, and a convergence-rate comparison across all five unconstrained methods.
momentum – Nesterov’s accelerated gradient and Adam.
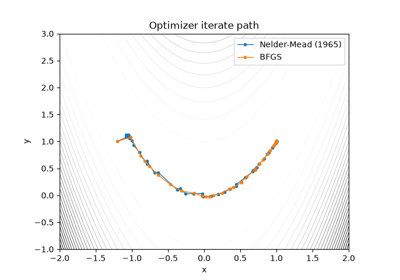
direct_search – derivative-free Nelder-Mead simplex search.
scalar_search – golden-section search in one dimension.
stochastic – Robbins-Monro stochastic approximation.
least_squares – Levenberg-Marquardt nonlinear least squares.
constrained – Lagrange multipliers, KKT verification, the penalty method, and the Frank-Wolfe method.
linear_programming – linear programming via
scipy.optimize.linprogand integer programming by branch and bound viascipy.optimize.milp.game_theory – zero-sum matrix games and the minimax theorem.
dynamic_programming – Bellman’s recursion for the knapsack problem.
Nonlinear conjugate gradient#
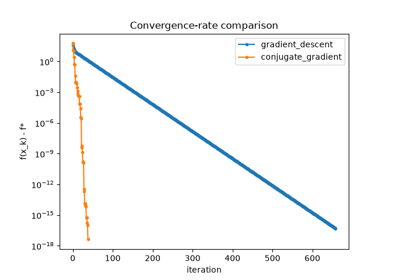
Fletcher-Reeves and Polak-Ribiere nonlinear CG.
Constrained optimization#
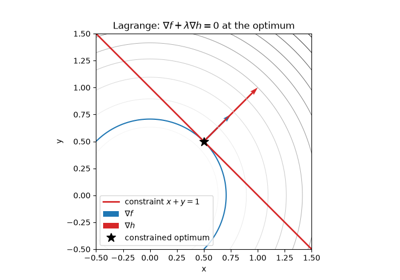
Lagrange multipliers and the KKT conditions, the Frank-Wolfe method, and the quadratic penalty method.
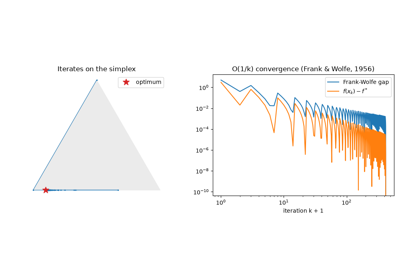
Frank-Wolfe: optimization over the probability simplex
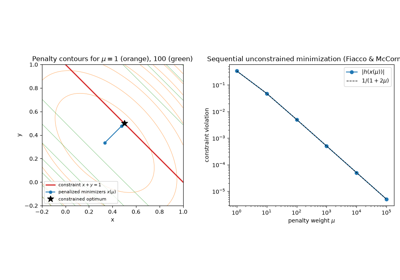
The quadratic penalty method: a sequence of unconstrained problems
Direct search#
Derivative-free minimization with the Nelder-Mead simplex method.
Dynamic programming#
Bellman’s principle of optimality applied to the 0/1 knapsack problem.
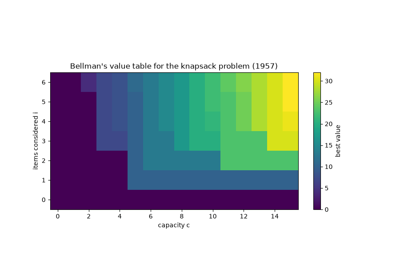
Bellman’s principle of optimality: the 0/1 knapsack
Game theory#
Zero-sum matrix games and von Neumann’s minimax theorem, solved as linear programs.
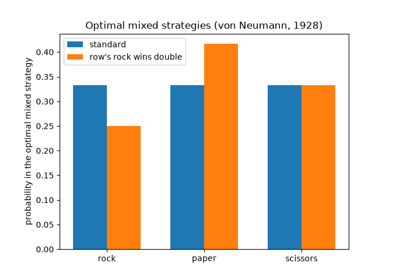
Von Neumann’s minimax theorem: optimal mixed strategies
Gradient descent#
Fixed-step and backtracking-line-search gradient descent.
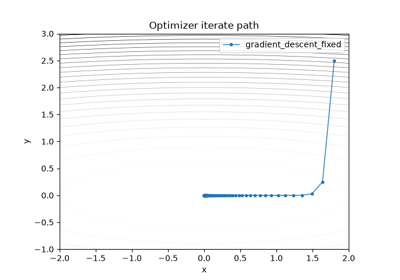
Fixed step vs. backtracking line search on an ill-conditioned bowl
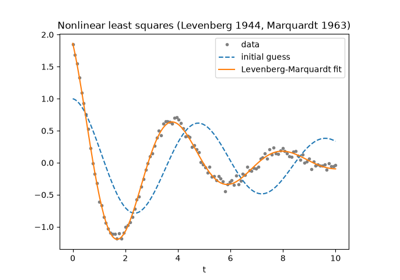
Nonlinear least squares#
Curve fitting with the Levenberg-Marquardt method.
Linear programming#
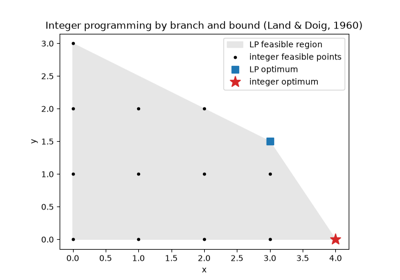
Dantzig’s simplex method and branch and bound for integer programs.
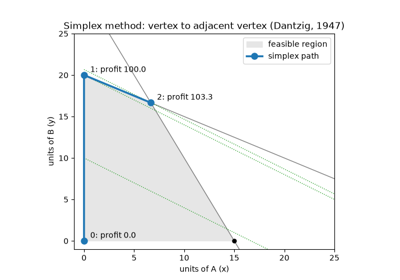
Dantzig’s simplex method: walking the vertices of a production LP
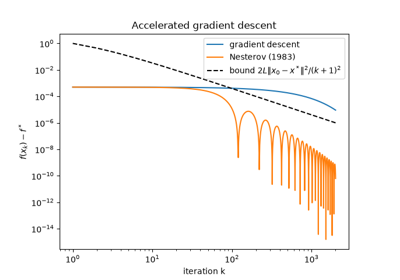
Momentum methods#
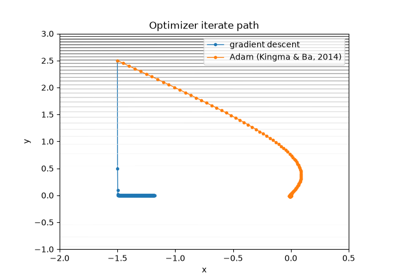
Nesterov’s accelerated gradient and the Adam optimizer.
Newton’s method and BFGS#
Quasi-Newton BFGS compared with Newton’s method and gradient descent on the Rosenbrock function.
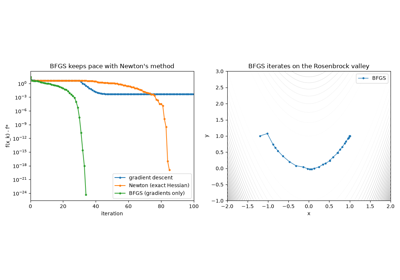
BFGS: Newton-like convergence without second derivatives
One-dimensional search#
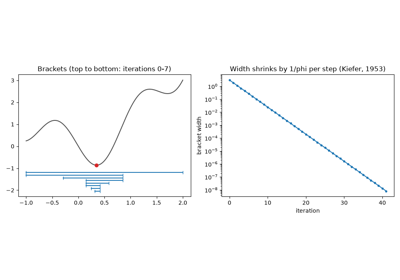
Golden-section search for the minimum of a unimodal function.
Stochastic approximation#
The Robbins-Monro iteration: stochastic gradient descent on noisy gradients.
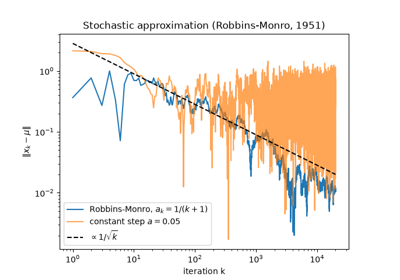
Robbins-Monro: stochastic gradient descent with decaying steps
Benchmark functions#
Rosenbrock’s banana function, the standard stress test for optimizers.
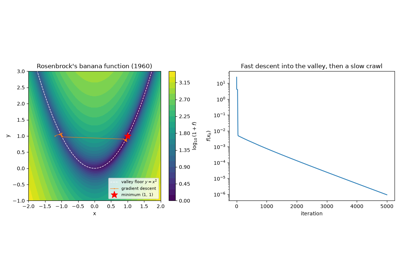
Rosenbrock’s banana function: a narrow curved valley